Planning for retirement in your thirties provides the benefit of more time to establish a financial cushion, while you also are responsible for paying your bills, buying a house and supporting your family’s growth. Earlier on, you will have the advantage of compounding over a number of years that could decrease what you need to invest at a later stage. Small, regular donations add up over time. Waiting to save for retirement could mean making much larger contributions to achieve the same goal. Knowing what you will need in retirement, what investments you can make, and what financial goals you have can help you develop a realistic retirement plan.
Why your 30s are an important time to plan
The 30s could be a time when income goes up, job advancement takes place, and financial obligations grow. While retirement may feel like the distant future, it’s a good time to build good saving and retirement plans.
The early beginning allows your investment to have a longer potential growth cycle. Perhaps, you won’t have to be making significant contributions at the beginning, as you have a longer horizon of investment.
How compounding supports early retirement planning
Compounding allows returns generated by an investment to remain invested and potentially generate further returns. Over a longer period, this can contribute significantly to the growth of retirement savings.
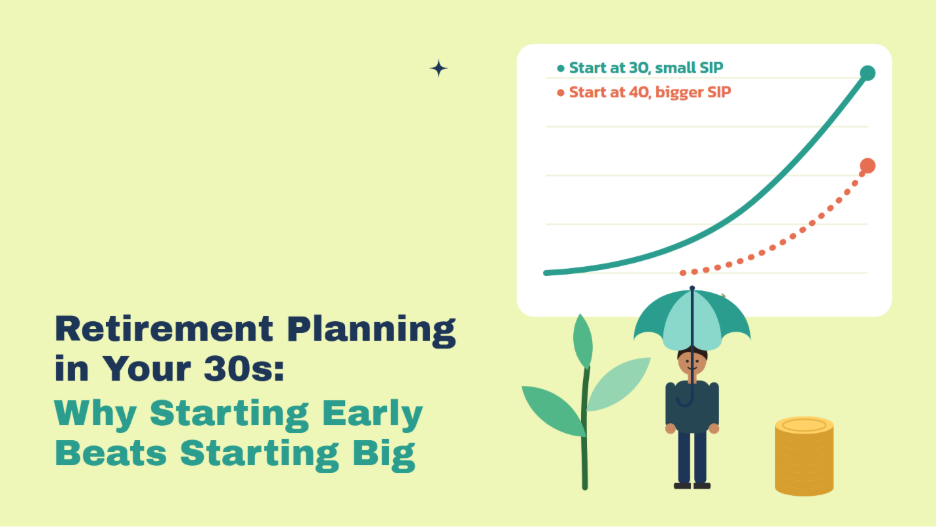
For example, suppose a person invests ₹5,000 every month from age 30 to 60 and earns a hypothetical annual return of 10%, compounded monthly. The accumulated amount could be approximately ₹1.13 crore. If another person invests ₹10,000 monthly from age 40 to 60 at the same hypothetical return, the accumulated amount could be around ₹76 lakh.
These are illustrations and not guaranteed returns. Actual results can vary based on investment performance, market conditions, taxes and costs. The example demonstrates why starting earlier can sometimes be more effective than waiting to invest a larger amount.
Estimate your future retirement needs
When planning for retirement, one of the first things you should consider is an estimate of your expenses when you stop working. These can consist of housing, health care, household costs, travel and support to members of the family.
When calculating the required amount, take into account your anticipated retirement age, your current living costs, your desired way of life and your savings. Re-check this calculation periodically, as income and responsibilities change.
Consider life insurance for financial protection
Life insurance is intended to be a death benefit that the beneficiaries of the policy are eligible for, provided the policy’s terms and conditions are met. Financial protection may be an important component of financial planning for those in their 30’s.
However, insurance and retirement investments have different purposes. A term insurance policy generally focuses on financial protection, while retirement investments are intended to build funds for future expenses. Your financial strategy should consider both aspects according to your circumstances.
Understand different retirement investment options
Retirement plans can include various savings and investment arrangements intended to support financial needs after employment. In India, individuals may consider options such as the National Pension System (NPS), Employees’ Provident Fund (EPF), Public Provident Fund (PPF) and mutual funds.
These options differ in terms of investment choices, liquidity, taxation, risk and withdrawal rules. NPS, for instance, is a regulated retirement savings system with specific withdrawal and annuity-related provisions. PPF has a defined tenure and an interest rate notified by the government.
Build a consistent monthly investment habit
Making regular contributions can help you to manage your retirement savings. When you begin to invest in your future, don’t wait until you have a lot of money coming in, start with a sum that you can afford.
As your income increases, you can gradually increase your contribution. For example, if a person begins with Rs. 5000 monthly, they may want to make a gradual adjustment to the sum from time to time as per their income as well as other financial obligations.
Review your investment strategy regularly
As your job and family life evolve, your financial circumstances may be impacted. What works for investing in your 30s can change as you reach retirement.
Periodical reviews can help you determine if your retirement savings are still on track to achieve your goals. Don’t buy and sell long-term investments based on market fluctuations.
Conclusion
Retirement planning in your 30s is not about investing a huge sum up front, but rather investing early, sticking with the plan and checking it periodically. Long-term planning can be facilitated by estimating future expenses, taking into account inflation and striking a balance between saving for retirement and other financial objectives. For persons with dependents and obligations, another key factor to take into account is financial protection. The individuals can explore life insurance products offered by Tata AIA, depending on the protection requirements and eligibility. It helps to periodically update your financial plan so your retirement plan follows your life path.
